

OneBlinc - Financial tools

- 672.00 Reviews
- 4.6
- Downloads
- 100,000+
Our take on OneBlinc - Financial tools from Appgk
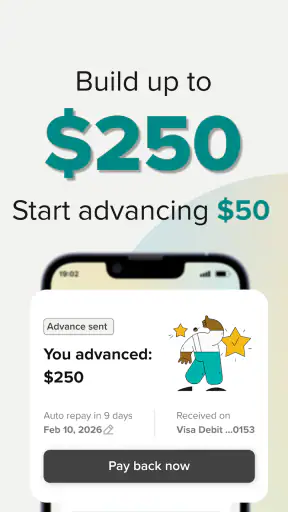
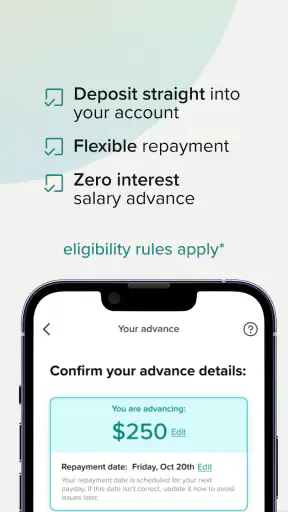
When an unexpected bill lands before payday, I understand why an app such as OneBlinc can look appealing. It is a finance app from OneBlinc built around accessing earned wages and sending up to 250 dollars to a linked account. I approached it less like a flashy banking replacement and more like a practical short-term cash-flow tool. That distinction matters: it may help bridge a timing problem, but it is not designed to replace budgeting, savings, or a regular bank account.
My overall impression is that the app is easiest to appreciate when you already know exactly why you need it. The central idea is straightforward, the interface is aimed at an everyday financial task, and the free download lowers the barrier to trying it. At the same time, anything involving wages, linked accounts, and urgent money deserves a slower look than a casual entertainment app. I would use it with a clear repayment or payday plan rather than treating available funds as extra income.
How OneBlinc feels in everyday use
Speed expectations when timing matters
The main appeal is speed of access, but I would be careful about interpreting that promise too broadly. The app’s purpose is to help you reach wages through a linked account, so the useful question is not simply whether the screens open quickly. It is whether the whole process fits your particular pay situation, account setup, and transfer timing. Those practical steps can matter more than the visual responsiveness of the app itself.
For a user who has already connected the relevant account and understands the amount needed, the workflow should feel more direct than applying for a conventional personal loan. There is no reason to approach it like a long-term borrowing product. I see the strongest use case as a small, temporary gap: a grocery purchase before payday, a utility payment that cannot wait, or transportation needed to get to work.
Best Parts of OneBlinc - Financial tools
Things to Keep in Mind About OneBlinc - Financial tools
One useful habit is to decide the exact amount before opening the app. Because the service allows access to wages up to 250 dollars, I would avoid automatically taking the maximum simply because it appears available. Requesting only what solves the immediate problem keeps the next payday easier to manage and makes the app a controlled tool instead of a recurring dependency.
Another practical tip is to check the linked account before starting a request. If your account details have changed, your usual account is temporarily unavailable, or your wage information is not presented as expected, the urgent part of the experience can become a troubleshooting exercise. I would rather discover that during a calm moment than while standing at a checkout or trying to pay a bill.
News and Features Related to OneBlinc - Financial tools

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What happens during heavier-use moments
Finance apps are often judged differently from social or gaming apps. A brief delay in a game is annoying; uncertainty around a transfer can be genuinely stressful. That is why I would test the basic navigation and account connection before relying on OneBlinc for an emergency. A quick exploratory session can show whether the app is comfortable on your phone and whether you understand the steps without pressure.
Heavy use does not necessarily mean opening the app repeatedly. In this case, it can mean checking eligibility, reviewing the amount, confirming the linked account, and following the progress of a wage-access request in one sitting. Those actions involve more attention than simply tapping a button. I recommend keeping your banking app available as a separate reference, so you can verify where money is expected to arrive rather than assuming that a completed request and a visible balance are the same thing.
Don't want to read the full review?
The app is also more suitable for planned short-term use than for a chain of emergencies. If rent, food, transport, and several other essentials all depend on repeated wage advances, the convenience can hide a deeper cash-flow problem. I would treat repeated use as a signal to review pay timing and expenses, not as proof that the app has solved the underlying issue.
A less obvious trade-off is psychological: immediate access can make a purchase feel affordable when it is only being moved earlier in the pay cycle. I would write down the amount and the date I expect normal wages, then check whether the following payday still covers fixed commitments. That simple step is more valuable than relying on the app’s convenience alone.
Screenshots
Reliability and the confidence to use it
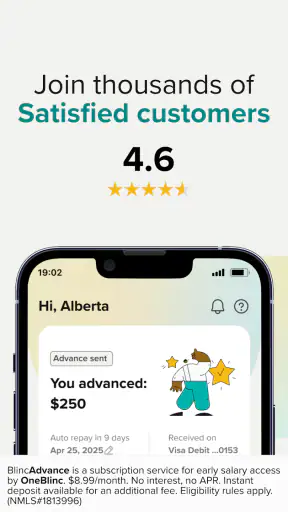
OneBlinc has a 4.6 average from around 4.8 thousand ratings, with more than 600 written reviews, and it has passed the 100 thousand install mark. Those figures suggest that the app has attracted a meaningful user base and that many people have found the experience satisfactory. They are useful signals, but they do not guarantee that every wage-access request will feel identical, because personal account situations can vary.
The developer is OneBlinc, and the app was released on February 18, 2025. Its current version is 7.12.0, which tells me that the product is being maintained through numbered updates rather than sitting untouched after launch. I still would not confuse an updated app with a guaranteed transfer outcome. Reliability here has two parts: the application must behave properly, and the financial connection must work correctly for your circumstances.
Before depending on it, I would make sure my phone has a stable connection, my linked-account information is accurate, and I have enough time to deal with an unexpected verification step. I would also keep confirmation screens or transaction references until the money appears where expected. That is not a criticism unique to this app; it is sensible behavior whenever an application handles access to wages.
Recovery is another important part of reliability. If a request does not appear to complete, I would avoid submitting several duplicate requests immediately. First I would check the app’s status, then the linked account, and only afterward decide whether another action is necessary. Repeating a financial request while uncertain about the first one can create confusion, especially when the need for money is urgent.
I also like to separate technical recovery from financial recovery. If the app closes or behaves oddly, restarting it and checking the connection may help with the technical side. If the balance or transfer status remains unclear, that becomes an account-support matter rather than something to solve by repeatedly tapping. Keeping those two problems separate makes the situation easier to manage.
Device constraints and everyday practicality
The minimum operating-system requirement is Android 7.0, so the compatibility range is relatively broad for people using older Android phones. The app is rated for Everyone, which makes its intended audience broad, although the financial decisions inside it still require adult judgment and careful reading. I would pay attention to how comfortably the app runs on an older device rather than assuming that a supported operating system guarantees a smooth experience.
On a phone with limited storage, limited memory, or an older battery, any finance app should be used with a little patience. I would close unnecessary applications before completing a wage-access request, especially if the phone is already struggling with account or browser-based screens. The goal is not to chase benchmark performance; it is to reduce the chance that a low-resource device interrupts an important financial step.
Resource demands are also about attention and connectivity. A weak signal can be more disruptive than a slow processor when you are confirming account information. I would avoid initiating a request in a place where the connection repeatedly drops, and I would not uninstall the app immediately after making a request if I might need to review its status. Keeping the app available until the transaction is clear is a small but sensible precaution.
People using iPhones or another mobile platform should check the appropriate store availability before planning around the service. I would not assume that an Android requirement describes every device experience. For Android users, the stated minimum of 7.0 is helpful, but the practical experience will still depend on the phone’s age, available storage, connection quality, and the condition of the linked account.
Where it beats usual alternatives
Compared with asking a friend or family member for a small amount, OneBlinc offers a more private and repeatable process. Compared with a traditional personal loan, it is aimed at a much smaller, shorter-term need rather than a larger planned expense. Compared with simply waiting for payday, its value is the ability to address a timing problem now. Those comparisons explain the app’s niche more clearly than calling it a general banking product.
That niche also defines its limits. If I needed a larger amount, a predictable repayment schedule, or a solution for ongoing debt, I would look at a regulated bank product, a credit union, or a carefully reviewed budgeting plan instead. If the expense could wait a few days, waiting would usually be simpler. If I needed to build savings, a wage-access app would not be the right tool because it moves money forward rather than creating new money.
The free price is another reason it may be worth examining, but free does not mean that every financial consequence disappears. I would read the in-app terms around access, repayment, and any account-related conditions before confirming a request. A no-cost download is only one part of the decision; the important question is how the transaction fits into my next pay cycle.
A realistic scenario for deciding whether to use it
Imagine I need 45 dollars for a prescription or a work-related bus pass two days before payday. I would first confirm that the expense is essential, check the linked account, and request only that amount rather than the full available limit. Then I would note that the money is an advance on wages, not a bonus, and make sure the next payday still covers rent, food, and scheduled bills.
In that situation, the app could be a reasonable bridge because the need is specific and the amount is modest. I would retain the request details, monitor the linked account, and avoid making another advance just because the balance feels temporarily comfortable. Once the normal wages arrive, I would review whether the app solved a one-off timing issue or whether my budget needs a more durable change.
Now imagine a different situation: I am short every week, using advances for several categories, and counting on the next request to cover the previous gap. I would skip OneBlinc in that case. The convenience might make the pattern less visible, while a conversation with a bank, credit counselor, employer, or trusted adviser could address the recurring problem more honestly.
Who should try it and who should skip it
I think the app is best for someone with a clear, short-term wage timing problem, a compatible Android phone, and enough discipline to request only what is necessary. It can also suit users who prefer handling a small financial need privately instead of borrowing from someone they know. The free entry point and broad age rating make it easy to investigate, but ease of access should not replace a personal affordability check.
I would be cautious if you dislike linking financial accounts, have unreliable phone connectivity, or cannot comfortably identify when the next wages will cover the advance. I would also skip it as a first choice for discretionary shopping, larger purchases, or recurring bills that are already difficult to meet. In those cases, the usual alternatives—waiting, cutting the expense, arranging a formal payment plan, or seeking longer-term financial advice—are more appropriate.
OneBlinc is not a substitute for a bank account, an emergency fund, or a complete budgeting system. Its strength is narrow and practical: it can help bring earned wages into the present when a small gap matters. Its weakness is the same narrowness, because it cannot turn an unsustainable budget into a sustainable one.
My performance verdict after weighing the trade-offs
From a performance perspective, I would judge OneBlinc by clarity and dependable recovery rather than by flashy speed. The app’s purpose is focused, its Android compatibility reaches back to version 7.0, and its rating and install history indicate that it is not an obscure experiment. Those are reassuring starting points for a finance tool that people may open under pressure.
Still, I would use it deliberately. Prepare the linked account first, request the smallest useful amount, keep a record until the transfer is visible, and avoid repeating requests when the status is unclear. Those habits address the real friction points more effectively than simply installing the latest version, which is 7.12.0.
My final view is positive but measured. I would recommend OneBlinc to a friend facing a genuine, temporary gap in access to wages, especially when the amount is small and the next payday is clear. I would not recommend using it as a routine spending cushion or as a replacement for longer-term financial planning. Used with that boundary, it feels like a focused financial tool; used without it, the same convenience can postpone rather than solve the problem.
OneBlinc - Financial tools FAQ
What is OneBlinc, and what financial tools does it offer?
OneBlinc is a financial services app designed to help eligible users manage short-term cash needs and everyday money matters from a mobile device. Depending on eligibility and location, its tools may include access to a paycheck advance, a spending account or card, budgeting features, credit-building resources, and other financial products. Available services, limits, fees, and terms can vary, so users should review the details shown in the app before accepting any offer.
Who can use OneBlinc, and what information is required to sign up?
OneBlinc is generally intended for users who meet its identity, income, employment, age, residency, and banking requirements. During registration, the app may request personal information, identification details, employment or income data, and permission to connect a bank account or payroll provider. Approval is not guaranteed, and requirements can change. Before downloading, confirm that the service operates in your country or state and that you satisfy its current eligibility rules.
Does OneBlinc charge fees or interest for its financial services?
The cost depends on which OneBlinc product or feature you use. Some services may include membership charges, transaction fees, expedited-funding fees, card-related costs, or other optional charges, while a particular advance may be presented under specific pricing terms rather than traditional loan interest. Because fees and conditions can change, carefully read the disclosure, repayment schedule, and agreement displayed before confirming a transaction. Never assume that every feature is free.
How does repayment work if I use a OneBlinc cash advance?
If you receive a cash advance through OneBlinc, repayment is normally scheduled according to the terms shown when the advance is approved. The app may collect the amount automatically from a linked bank account or another authorized payment source on the due date. Users should make sure sufficient funds are available and understand what happens if repayment fails, including possible additional charges, account restrictions, or repeated collection attempts.
Is OneBlinc safe to use, and what should I consider before downloading it?
OneBlinc uses account verification and security controls intended to protect personal and financial information, but no financial app can eliminate every risk. Download the application only from the official Google Play Store or Apple App Store, check the developer name, and review requested permissions. Also examine privacy practices, customer-support options, pricing, repayment terms, and user reviews. Avoid sharing login codes and contact support promptly if you notice suspicious activity.











